 My Patrix site
Breaking the Law
For the first time in many years I feel that there is some potential uncertainty in the results Apple will announce. After a period of excellent accuracy (shown in graph below), the company’s guidance has begun to diverge dramatically from reality and the trend might continue this quarter. The cause might be unanticipated demand for the iPhone 6/6 Plus. The growth rate for the product was 46% in Q4 and 40% in Q1. This is unanticipated because growth rates have been below 20% for five quarters and below 50% for eight.
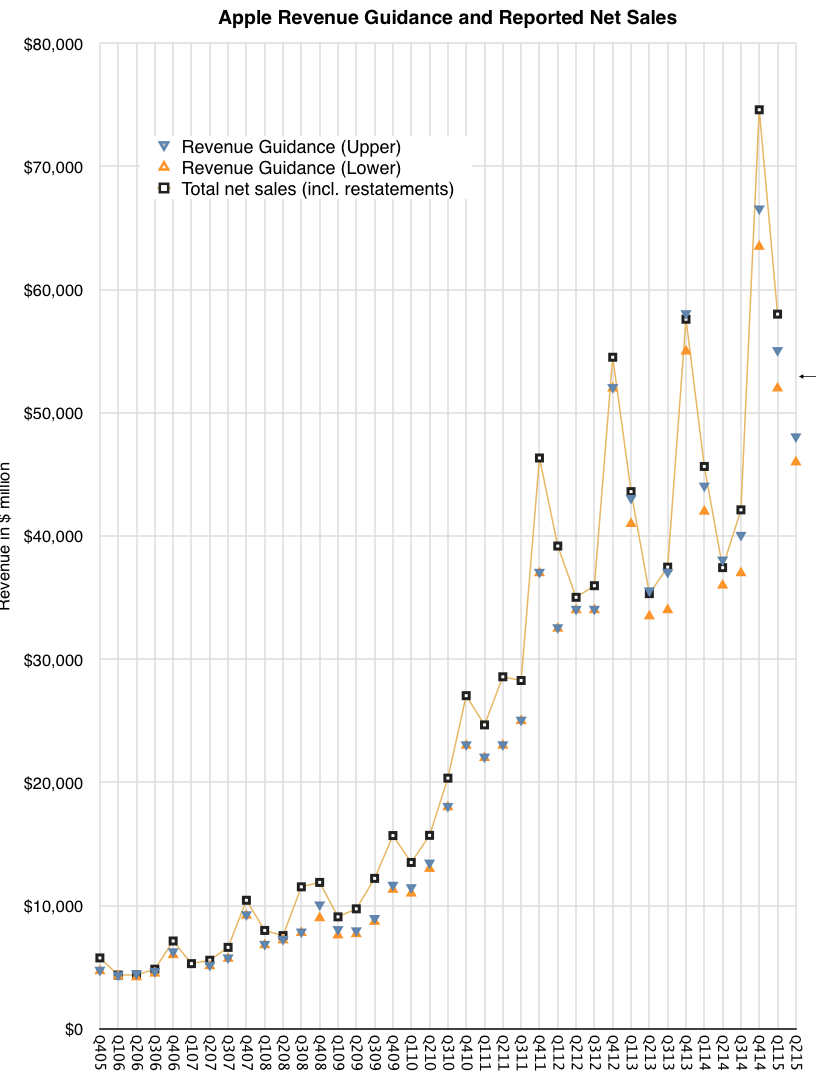
This slowing of growth was explainable given the rate of diffusion of smartphones in the global population. Within the US and some other early adopting economies the market is reaching late stages where most people have switched to smartphones. Globally we are at a more modest 30% or so but in many of the late adopting economies Apple does not have wide distribution.
Of course this thesis is thinly supported. There are many reasons to think that late adopters would still start with iPhone and that earlier adopters of Android would upgrade to iPhone after a few purchase cycles. Thus, the iPhone could prosper in later-adoption or even in post-saturation states of the market.
Indeed, in the post-saturation PC market, Apple is doing very well with the Mac and in the late to post-saturation MP3 player market the iPod did extremely well. This suggests that when it comes to value capture brand, experience and satisfaction trump function, price and share considerations in almost all consumer markets ((Enabled by design for jobs to be done. See non-technology markets for abundant evidence of this. ))
With so many assumptions put asunder the iPhone business suddenly looks downright lively. I adjusted my own growth assumptions and the resulting figures are shown below.
F3Q15
Daniel Tello
Horace Dediu
iPhone
Units
51.0
52.8
Price
626
645
Revenues
31925
34059
iPad
Units
10.0
10.6
Price
428
430
Revenues
4280
4567
Mac
Units
4.95
4.94
Price
1240
1240
Revenues
6136
6129
Services
Revenues
5006
5196
Other
Revenues
3902
3092
Total
Revenues
51249
53043
COGS
30577
31766
GM
40.3%
40.1%
OpEx
5733
5789
OpInc
14939
15488
OI&E
357
350
Pre-tax
15296
15838
Tax
4023
4165
NetInc
11273
11673
Shares
5779
5780
EPS
1.95
2.02
I include for comparison Daniel Tello’s forecast as his work carries quite a bit of thoughtful analysis.
The upshot of this is that the company is poised to grow earnings per share at a rate of at least 50%!
That growth rate is astronomical, especially for what is already, by far, the world’s biggest company by market capitalization.
This was not supposed to happen because of a so-called “law of large numbers.” The “law” is actually a probability theorem which states that the average of experimental results should be close to the expected value given sufficiently large number of experiments. The way it’s applied in market analysis (I assume) is that “no company can perform above market average performance for a sufficiently long time”.
It implies that there can be no outliers and that all companies “revert to the mean because …”
Actually, I don’t have any idea why they might. The premise that all companies are the same must play into this but companies can only be alike if they have the same processes, priorities and resources. As long as I’ve been able to observe and as much as I’ve ever read on the subject I have never encountered any two which had anything in common.
And so the law of large numbers, as applied to market performance is a myth. It is easily disproved with a simple deconstruction into the causes of firm performance, but the empirical data from Apple alone shows how foolish it is to believe it.
Comments