 My Patrix site
The Puzzle of Sustainable Growth
20 more years at 24%?
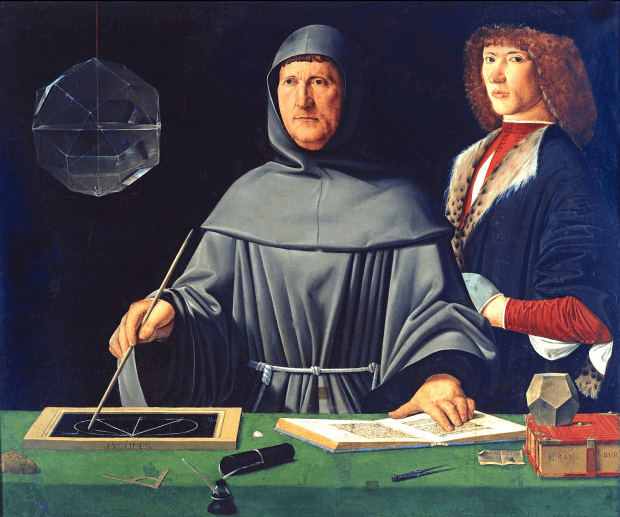
Summa de arithmetica, geometria, proportioni et proportionalita (Summary of arithmetic, geometry, proportions and proportionality) is a math book written by Luca Pacioli. It is a compendium of the mathematics that was known in Renaissance Italy. This included practical arithmetic, basic algebra, geometry and accounting. Written as a textbook and reference work, it was first published in 1494, two years after Columbus landed in the new world.
As Venice was an early adopter of the newly invented printing press, it was originally published there with a second edition printed in 1523 in Toscolano. About a thousand copies were printed, of which roughly 120 still exist. This was an extraordinary large run for the time and, in contrast to pre-press era when maybe 10 copies would be hand-made, it was a bestseller.
Why was a math book so popular?
First, because it was in Italian rather than Latin. Second, within the chapter on business, a section entitled Particularis de computis et scripturis (Details of calculation and recording) describes the accounting methods then in use among northern-Italian merchants, including double-entry bookkeeping, trial balances, balance sheets and various other tools employed by professional accountants to this day. The business chapter also introduces the rule of 72 for predicting an investment’s future value.
Regarding this rule, the quote is:
In wanting to know of any capital, at a given yearly percentage, in how many years it will double adding the interest to the capital, keep as a rule [the number] 72 in mind, which you will always divide by the interest, and what results, in that many years it will be doubled. Example: When the interest is 6 percent per year, I say that one divides 72 by 6; 12 results, and in 12 years the capital will be doubled.
What it says is that if you want to know how long you need to wait for an investment to double, divide 72 by the interest rate. If the (compounded) interest rate is 6% then wait 72/6 or 12 years and you double your money.
This is a great rule of thumb and was devised before logarithms were invented which are more precise but harder to calculate. Even today this is a great rule and should be used instead of relying on spreadsheets or AI to get a quick answer. The accuracy is highest at interest rates above 5% which is well within investor rates of return.
Once you develop an intuition about time to double the interest (or rate of return) becomes a measure of time which is much more relatable. The investment thesis then becomes one of duration which rewards patience rather than gratification.
The problem is however that this rate of return must be maintained and compounded throughout the period. When it comes to returns on share prices, the rate of return can vary greatly and does so instantly and continuously during trading.
Balanced portfolios, index funds, etc. attempt to smooth out the variability and provide a predictable rate of return. For instance, the S&P 500 index, since its adoption of 500 stocks in 1957, has had compounded annual growth rate of 10.56% (excluding inflation). The 10% rule of thumb has been used to encourage investors to hold fast through long periods. At this rate the rule of 72 means you double your money every 7.2 years.
This is also used to discourage “stock picking” because individual stocks are both more volatile and more susceptible to disruption, exiting the index at an alarming rate. Indeed, disruption theory suggests that companies are surprisingly fragile insofar as they succumb to mismanagement with uncanny regularity.
Think of it another way: if it were not for disruption, a public company is a remarkable money printing machine. If it gets to a point of success, it should deliver constant growth consistently. Even 15% growth would mean investors would double their money every five years. That would allow $2000 to become $1 million in 50 years. A single stock purchase at age 15 would provide the individual a fully funded retirement.
The answer is that innovation theory is a theory of competitive behavior and that external factors force time horizons to be not long enough to preserve sustainable compound annual growth rates beyond a few years. Technologies change, people change, tastes change and management is distracted or unable to adjust to these changes.
Let’s look at Apple as an example of consistency of return.
You should ask what is the rate of return on Apple shares in the same way that the S&P 500 index is measured (since 1957) to have a 10% compounded annual growth rate (CAGR). I went through this exercise for the last 20 years: Assuming investment during the last week of each year, what would the compound rate of have been today?
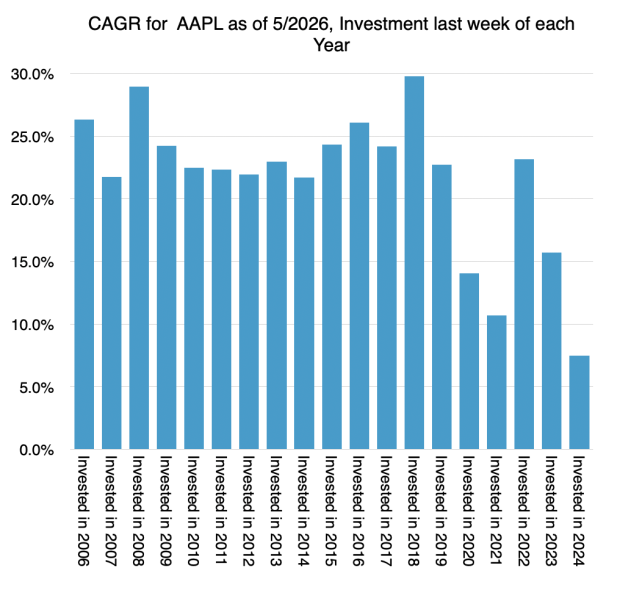
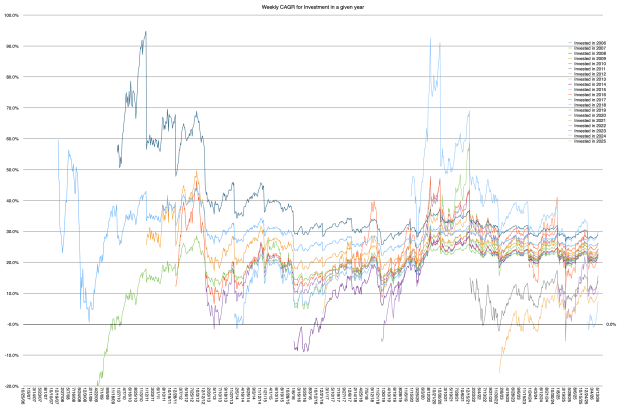
I graphed both the instant return for any point in history (the second graph) and return as of today (the end points of the second graph are shown in the first).
The answer is: For investments longer than 1 year, the average is 21.6%. For holding longer than 5 years the average is 23.6%. For holding even longer, it does not drop much below 24%. Note that as investments are made, short-term they can be far above or far below the median rate of return. they tend to converge on the median over time. And what a median that is!
If we use the rule of thumb that long-term investments in Apple have yielded about 24% then the rule of 72 means you double your money in three years, every three years.
This is extraordinary not just because of the 24% CAGR but that it has been going on for about 20 years.
The puzzle that Luca Pacioli and his students in Renaissance Italy must have considered has been the same as the one we have study today: How do you maintain that interest rate and hence that doubling period for long enough to benefit from it?
The question has always been about sustainability.
This is the question at the heart of Warren Buffett’s investment thesis. He called it a moat. It’s at the heart of management theory and it’s called sustainable competitive advantage. And it’s at the heart of Apple investment. Especially as the company was known as a hit-driven business. Hits are nice but they are not likely to be consistent. It’s why it’s had a low P/E ratio even though it was booming.
Apple has always been a tough thing to invest in.
But there is hope…
The rest of this post is for Asymco members. Continue reading on asymco.com.
Comments