 My Patrix site
Why all-in and why all are in
Take all my money, please.
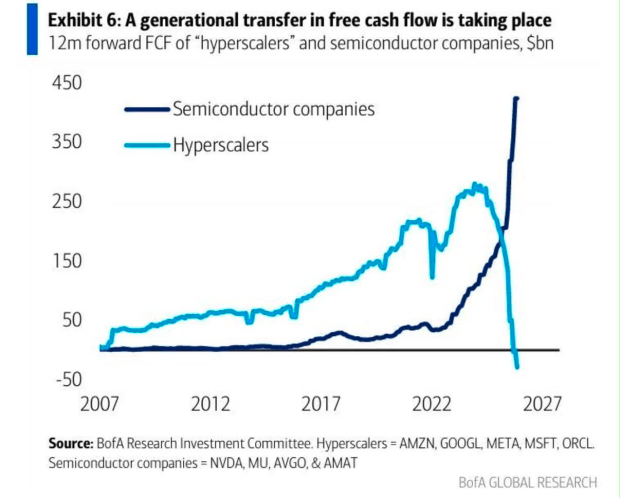
The graph above shows that Amazon, Alphabet, Meta, Microsoft and Oracle decided to transfer their shareholders’ wealth to the shareholders of Nvidia, Micron, Broadcom and Applied materials1. This is not an exaggeration. Free cash flow is wealth and it belongs to shareholders. The transfer is real since the capital expenditures undertaken with this cash flow by these “hyperscalers” have gone directly to create unprecedented windfall profits for semiconductor companies. So much so that the companies receiving these windfalls are scrambling to give it to their shareholders (and employees.) And the scale is astonishing! These companies alone are moving hundreds of billion, more than the profits gained in the semiconductor businesses in decades.
Prof. Clayton Christensen had a theory he called “the dumb manager theory” to describe what most people use to explain why companies fail. According to this theory when a company is successful it’s because its managers are smart. Conversely, when a company is failing it’s because its managers are dumb. The problem with the theory is that it’s usually the same managers who are there when a company succeeds as when it fails. Believing in the theory implies that you also believe that smart people can turn dumb. But you can’t tell when and why this happens so determining success depends on your skill at psychoanalyzing managers.
The second problem with the theory is that when one company fails, many other companies in the same industry fail as well. Yes, Kodak failed to grasp digital photography and its management has been skewered for it. But so did Fujifilm in Japan and Agfa in Germany. Did all these managers get together at a dumb management conference and agree to do the same dumb things at the same time? Clay Christensen asked if it’s possible that they colluded to fail. He noted that he’s often heard of collusion in order to succeed but never of collusion to fail.
So the dumb manager theory of success and failure of businesses is problematic. When successful companies fail, it’s not likely due to managers losing their competencies. Indeed, it may be because they are too competent.
Disruption theory holds that companies fail precisely because managers pay too close attention to targets that are no longer relevant. And the “collusion” aspect is that all managers become fixated on the same target at the same time because they are all trained in the same way. There is group-think but also group-obsession on metrics and best practices and theories of the market that no longer apply.
In the current wealth-transfer spectacle, managers at companies which are at the “top of the stack” offering complex, multi-faceted, multi-sided marketplaces of services to billions of consumers and businesses and advertiser customers through multiple channels of global distribution chose to give all they have2 to the “bottom of the stack” commodity semiconductor designers and manufacturers. The very businesses that they chose not to participate in and which a multitude of advisors, analysts and academics told them for decades are worthless metal benders.
This new logic is that by directing all their capital to the bottom of the stack they will ensure continuing success of their complex top-of-the-stack business.
The irony should not be lost on the reader.
It’s not just a question of “what if they’re wrong?” The paradox is why is the plunge so headlong, so reckless. I.e. why is it not calibrated to an abundance of evidence of returns on the risk taken and, moreover, why is the belief so universally held.
In other words, why all-in and why all are in.
Of course, there is one anomaly: Not “all” are in. Apple is not all-in and it’s the only one of the Magnificent 7 that is conspicuously hedging on this wealth transfer.
Apple may be the anomaly that answers the paradox. The reason Apple stayed out will not be found in the “wise manager theory” of avoiding failure.
Apple preserved its shareholders’ wealth because they focused on their customers. (Yes, quite an anticlimax.)
The rest of this post is for Asymco members. Continue reading on asymco.com.
Comments