 My Patrix site
Why is there no Apple Car?
There are some industries that can’t change.
Yesterday, Tesla reported its second quarter earnings and there were few surprises. The company’s automotive business is as structurally unsound as ever. Despite automotive deliveries and revenues growing at 25% (from a very weak Y/Y comp.), Tesla only saw a 1.4% operating margin in Q2. The gross margin fell slightly but the operating income fell by 57%. Excluding regulatory credit sales of $146 million (which should disappear soon), the operating margin was only 0.7%. The days of automotive profit, never mind extraordinary profit, are gone.
Cash flow went negative at -$1.1 billion. GAAP net profit of $1.1 billion was down 6% YoY, only because of a $1 billion unrealized gain in SpaceX shares, which, if excluded, would reduce net profit to $0.35 billion, or 70% lower than Q2 2025. Shares fell 14.5% the following day and the P/E ratio fell from 350 to 335.
Tesla Bulls would argue that these metrics are not relevant because the company is in the middle of a pivot from products to services. The product business will gain its margins from subscriptions (FSD) and ride sharing (Robotaxi). Current manufacturing overcapacity (mainly due to failed Cybertruck) will be reallocated to robotic taxis and humanoid robots. Until these arrive, the metrics should be ignored. This much is already reflected in the share price as its P/E ratio is beyond reason.
But are there other metrics we should look at besides selling cars that back this up? Robotaxi and Optimus humanoids are still not businesses contributing revenues so we can’t yet measure their take-up rate. FSD subscriptions, on the other hand, are being sold and there is excitement regarding the latest numbers. At the end of last year there were 1.1 million FSD subscribers and now, six months later, the total reported was 1.48 million. The history is shown in the graph below.
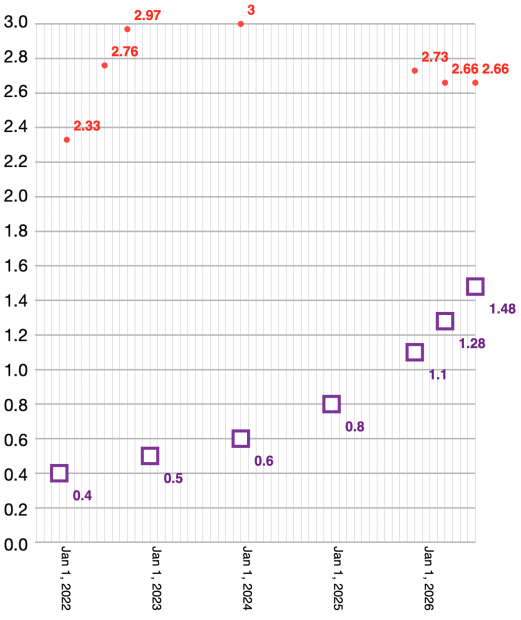
It shows a nice acceleration for FSD, shown in purple squares.
But not all accelerations continue forever. As a caution, I added a second data set shown in red. It represents the number of subscribers to Peloton. Peloton was quite a darling of the tech/investor community six years ago. After going public in 2019 at around $25/share the company climbed to $150/share by end of 2020 aided, no doubt, by the pandemic. It was seen as a major “disruption” in fitness. Today the shares are $6.
The problem with Peloton was that it could not break out of a small number of relatively wealthy users and its product was disrupted by much cheaper and easier to adopt wearables which could be hired for similarly motivating exercise.
By 2024, after following the classic accelerating curve, the Peloton subscriber base peaked at 3 million. That’s about twice the FSD base today. It’s not impossible to imagine Tesla reaching 3 million subs by 2028, seven years after launching as a monthly software subscription. Peloton itself took a decade to peak subs. But how high can it go?
If I add a few other user bases and their histories to the graph above we can see what scale can be achieved overall. (Click image for higher resolution.)
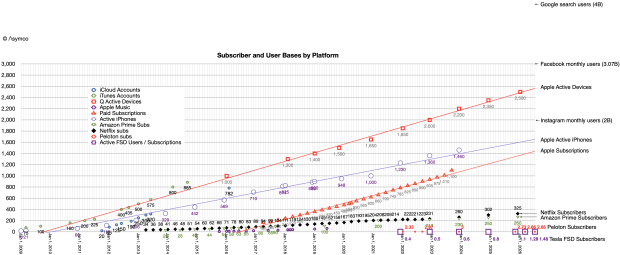
The highest user number is arguably Google with 4 billion. Second is Facebook with 3 billion, though as part of Meta’s overall 3.4 billion users of which 2 billion are Instagram users. These are not paying customers (rather, they are being sold) so the largest paying community of users are those from Apple with 2.5 billion active devices (users may be about 1.4 billion).
Active Apple subscriptions are 1.4 to 1.5 billion. PC users are about the same level.
Next would be Netflix with 325 million subscribers as of end of 2025 and Amazon with about 260 million subscribers. Note that Netflix and Amazon are growing but not accelerating suggesting they are nearing saturation.
Compared to these Peloton and Tesla are minuscule, indeed invisible on the graph. As a result the numbers are way too small to support what would be called an ecosystem–the attraction of third parties to develop on a platform. But why couldn’t Tesla reach billion user numbers with FSD? The answer is structural.
The reasons are that neither exercise equipment nor automobility create consolidated, uniform, global, iterative, rapidly evolving opportunities. The products can’t be obsoleted quickly enough. They are too bulky and expensive to be sacrificed for better versions. Cars are only owned by 1.2 billion people but the industry is very fragmented and becoming more so. There are hundreds of brands from dozens of auto groups with protected home markets and restrictions on distribution. Each brand has to field dozens of models which fragments the platform even more so that each product can only gain single digit million install base at best. That product has to stay in use for decades, often with to software upgrade path beyond the first few years. As a result even a prominent brand such as BMW can only create an overall customer base of 50 million users.
Tesla has barely 10 million users today1 and the total is not growing more than 2 million/yr. FSD is not even available outside the US, which is about half the install base23. Given this, the 3 million subs by 2028 might be a stretch.
Thus there isn’t a critical mass in the “owned” car market that creates network effects for services and ecosystems.
What about robotic cars?
That market is yet to be measured. We can start with the taxi market and that’s not very encouraging. The total professional taxi fleet globally is about 18 million, constrained by regulations. In addition, there are about 15 million active ride-hailing drivers world-wide4. They largely unconstrained by regulation but limited by economic value. If robot taxis were to replace this market5, it would not be huge enough to move toward a billion users. If it tries to replace owned cars the business has to contend with the fact that ownership is not just the utility of transport6. It’s a market for smiles not miles.
And then there is the rate of change. Nothing happens quickly in transportation–the bigger the vehicle, the slower it evolves. I should also note that Tesla is 23 years old, about half the age of Apple. Ten million customers in 23 years isn’t enough.
But the sclerotic automobility world is not alone .Many other industries suffer from sclerosis: housing, aviation, medical equipment, education, peacetime defense, etc. They cannot be consolidated, are not uniform, are not global, are not iterative and are not evolving rapidly enough to cope with silicon and software evolution cycles. Compare any of them with the smartphone or AI industry.
Indeed the idea of growing billion-customer bases within a decade or two is extremely rare and the exception rather than the rule. I’m guessing the challenge of adhering a service business onto the structural mess that is automobility is the primary reason Apple abandoned the idea of making a car.
Comments