 My Patrix site
What’s so special about Apple Upgrade?
What has servitization ever done for us?
Necessity is the mother of invention but return on invested capital is the mother of innovation.
Invention is big ideas with unclear benefits. Innovation is big benefits with unclear ideas. This is why inventions are easy to point out but hard to find useful while innovations are very useful but hard to explain.
Innovation is a matter of many small changes with big returns. The bigger this ratio between return and change, the more profound the innovation. Moving from selling music on physical media to digital files and then to subscribing to an infinite catalog is an example. Moving from hardware warranties to AppleCare subscriptions is another. Overall, the entire Services business is the best example.
Services has delivered a compound growth rate of 20% for 20 years, growing from $3.3 billion in 2006 (as iTunes Software and Services) to $120 billion for the last twelve months. Along the way, the gross margin on Services has increased to 75%.
A 20% compounded growth rate for 20 years with 75% margins is a strong indicator of innovation. Yet, there is hardly any accounting its components. Hardly and single thing to point to as the “big idea”. I tried for decades to provide a view into Services, such as it is:
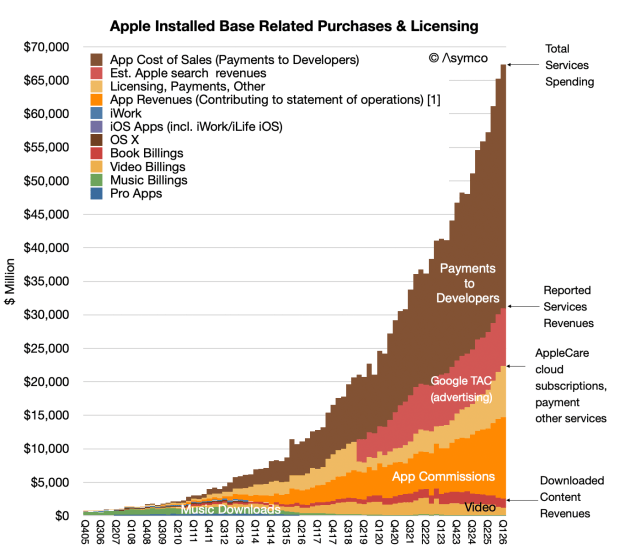
Moreover, Apple’s own Services category of revenues is but a small part of the activities on top of the stack of products and services that enable third parties to provide additional value. I call this the Apple Ecosystem and it is approaching $2 trillion/yr.
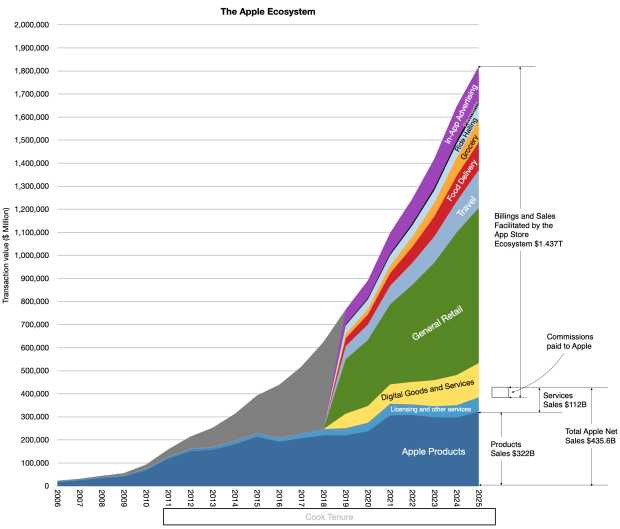
The servitization of music, warranties, television, storage, food, travel, transportation and many other products is unrelenting and extremely valuable but we can’t point out what one thing made it possible.
It’s a lot of small things. But one of these things just arrived and most did not notice it.
The innovation is the servitization of Apple’s core Products (shown in the bottom of the graph above). The brand is Apple Upgrade.
Apple Products, iPhone, Mac, iPad, Wearables & Home have still been mainly sold individually. A cumulative total of at least 5.2 billion devices of which 2.5 billion are still in use. Each requires a single initial purchase decision from one of 1.5 billion customers. The product then follows a life of use and perhaps a change in user with a secondary purchase decision. Finally it enters a disposal state where it might be recycled.
That’s a difficult picture to see. Many participants are involved beside Apple and the initial buyer. Many distribution channels, many secondary markets, many resellers, etc. This is why the products business has not been “servitized” or turned into a service. Services are more predictable but they require management and management depends on data. Apple keeps a relationship with the user once they are registered through iCloud but the path of the product itself is often invisible.
That is what is about to change.
The mechanics, trade-ins, monthly financing, hardware upgrades, aren’t new. Apple has offered versions of all of them for years. What’s new is a subtle change in defaults and what it means for who captures the residual value of a returned device.
Economically, the iPhone Upgrade and iPhone Payments programs are the same as Apple Upgrade. The purchase is “fiancialized” where multiple payments are substituted for a single purchase. But with the older system, only the iPhone was included and the product was default “owned” by the user during the loan period. Apple Upgrade applies to many, almost all, products and the default is that Apple “owns” the product until the finance (lease) term ends.
This ownership comes with risks and rewards. The risk is that the product is damaged, defaulted on or impaired in some way before the term ends. The reward is that there is control over its use after it is returned. The assumption is that the vast majority are returned and not bought-out and that is because of the attraction of new versions and the simplicity of rolling over a new lease.
Therefore the residual value is available to Apple but also access to inventory for resale. The used and refurbished phone market size is estimated at $65.20 billion and 315 million units in 2025 and expected to grow to $70 billion in 2026 and is forecast to reach $100 billion by 2031. That estimate might be low if Apple Upgrade grows rapidly.
iPhones account for roughly 40% to 50% of the global secondary, used, and refurbished smartphone market. That estimate implies that one used iPhone is sold for every two new iPhones. If one were to add the secondary market to the primary, iPhone unit sales are 450 million/yr.
The demand is such that Apple could increase sale (together with resale) volumes by 30% rather than the 15% for new alone. Demand from non-consuming markets in particular could drive this secondary market.
Naturally, the margin on the secondary markets will be lower than the primary but it may be a very sustainable and additive margin. Moreover, the relationship with the customer would be created at purchase time and could lead to a future upgrade path. For instance sale of AppleCare, accessories and personalization. The customer creation process would be better managed and more predictable vs. the third party resale channel.
The knowledge gained would also inform decision making. Usage patterns, pricing, mix, all benefit from perfect visibility into the secondary market. Apple is the one handling the sale, the device setup, the AppleCare pitch, and the accessories conversation. It also knows exactly when that customer is coming back.
This benefit would not appear if the Upgrade program proves unpopular. But that is why the Apple Upgrade is such a good deal. Almost too good.
Effectively, Apple Upgrade is free financing. Instead of paying upfront, the buyer pays monthly but not more than what the product is priced at. Apple is effectively eating the cost of the capital.
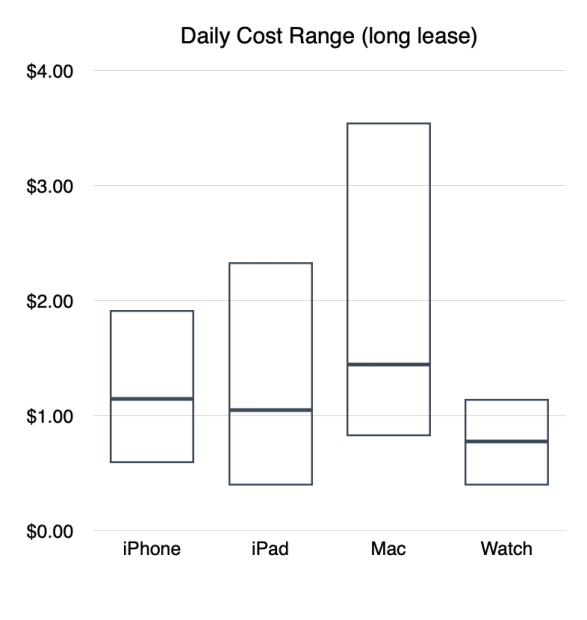
The optics of a price that is almost $1/day, easily calculated, will be very compelling. Apple Upgrade product daily pricing distribution is shown below:
The rest of this post is for Asymco members. Continue reading on asymco.com.
Comments